Florida Carpentry Contractor Insurance quote and information.
- How do insurance companies define Carpentry Contractors?
- What risk exposure do Carpenters have?
- What is the price of Carpentry Contractor insurance?
- Is insurance for Carpentry Contractor required in Florida?
- What coverages are common to Carpentry businesses?
- My dad has a business where some fiberglass work and carpentry work is done we have 2 guys that come and work with us and they get a 1099. Do we have to have workers comp? We do have liability insurance Thanks, being harrassed from the owner of the whole property who allows others on their property with just liabilty.
- Can you provide insurance anywhere in the state?
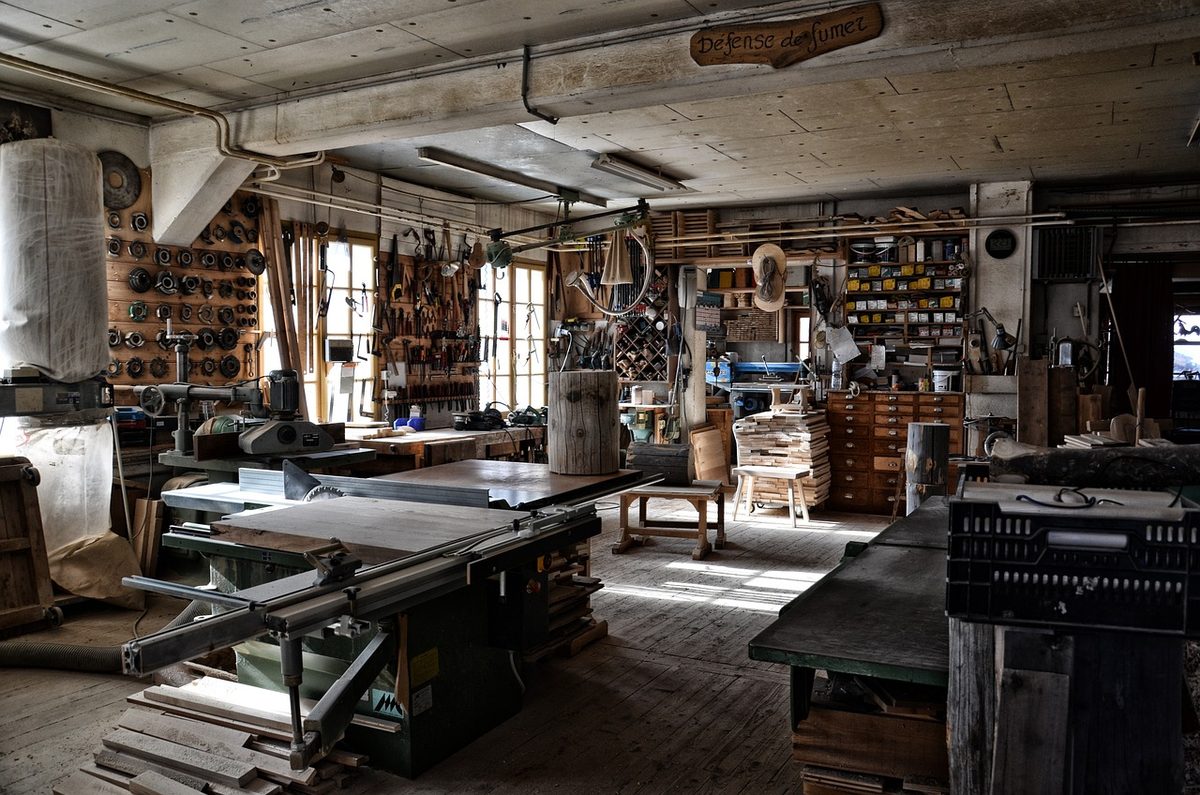
How do insurance companies define Carpentry Contractors?
Carpenters may perform interior work only, exterior work only, or both. Exterior carpentry includes framing work, such as building the structural support for a new building, structure or addition. Interior carpenters perform remodeling, repair or finishing.
Interior carpentry normally consists of either rough or finish work. Rough carpentry involves framing in windows and doors, laying floor joists and sub-floors, building stairs, etc. Finish work involves hanging doors, installing baseboards and molding around doors and windows, and making or installing cabinets, shelving or other built-ins. Make sure you protect your business with Florida Carpentry Contractor Insurance.
Have a Quick Question?
What risk exposure do Carpenters have?
Property Exposures
The carpenter’s own location usually consists of an office and storage for materials, equipment and vehicles. If the carpenter does woodworking at the shop, there is a heavy fire exposure. A careful review of the dust collection system is mandatory. So is a review of how flammable varnishes and glues are separated and stored.
Some carpenters store lumber in their yards. The more lumber on site, the higher the potential for loss, so base the review on the amount of storage and the method. Carpenters often use three-sided structures, which are highly susceptible to wind damage.
Inland Marine Exposures
Inland marine exposures center on three areas: owned or rented tools and equipment, building materials (builders risk or installation exposure), and materials transported to and from the job site.
Carpenters’ tools and equipment are heavy but relatively easy to transport. However, there can be a significant exposure if the carpenter transports lumber or woodwork done at the shop. Shifting and oversized loads and improper loading or tie down all pose a serious loss potential.
Equipment at a job site may be subject to drops from heights, weather damage or being struck by vehicles. If equipment and supplies are left at job sites, weather damage, theft and vandalism are common perils.
Premises Liability Exposures
Premises liability exposures at the carpenter’s shop or office are light unless there is woodworking or lumber storage. The potential fire hazard affects not only the insured but also neighboring businesses or homes. Controls in waste collection and fire control are important to protect the neighbors. Outdoor storage may create vandalism and attractive nuisance hazards that you must protect against.
Job site exposures include injury to the public or to employees of other contractors, and damage to their property or completed work. Tools, power cords, building materials and scrap all pose trip hazards. Saws and other power or hand tools are hazardous to bystanders and other subcontractors on the job site.
When installing or remodeling at a customer’s existing building, a buildup of dust and scraps is a potentially catastrophic fire and explosion hazard. Finally, examine the use of subcontractors and any contractual liability exposures.
Completed Operations
Completed operations is an important exposure. The carpenter may provide the framework upon which others build. Quality control is necessary, as is full compliance with all construction, material and design specifications. Poor record-keeping may force you to pay otherwise questionable claims. Inspection and acceptance of the work by the owner or general contractor are especially important. Inadequate monitoring of work orders and change orders may also be a concern.
Automobile Exposures
Automobile exposures are limited unless the carpenter transports lumber and pre-made items. Hazards include failure to secure the load properly and equipment failure, especially tie-downs and hitches. Poor selection and training of drivers, or inadequate supervision, poses a significant risk, especially with oversized loads.
Failure to monitor driving records or to ensure drivers have the appropriate license may also be a concern. Consider the age, condition and maintenance of the vehicles.
Workers Compensation
Hazards vary based on the size and nature of the job. Work with hand tools and sharp objects (e.g., saws and nails) is common to all types of carpentry. Lifting injuries such as hernias, strains and sprains may also occur, as may back injuries. Minor injuries may be frequent even when you control the severity exposure.
The absence of basic safety equipment may indicate a morale hazard. Examples are properly installed guards, steel-toed shoes and eye protection. Employee selection, training and supervision affect the loss potential.
On some jobs there may also be work at heights and potential injury from the carelessness of employees of other contractors. Occupational disease exposures include noise, dust and chemicals (e.g., working with pressure-treated lumber).
Make sure you have the correct Florida Carpentry Contractor Insurance policy for your needs.
Have a Quick Question?
What is the price of Carpentry Contractor insurance?
There’s no single price, because insurers rate each carpentry business on its own details. The biggest factors are the ones our quote form asks about:
- Your payroll and number of employees, which drive the workers’ compensation premium
- Your annual revenue
- How much of your work is residential or new residential construction
- Whether you work above three stories or do any roofing
- Whether you use subcontractors and whether they’re insured
- The liability limits you want
- Your years of experience
- Your claims history
Send us those details through the quote form and we’ll compare options from the insurance companies we represent.
Is insurance for Carpentry required in Florida?
Carpentry is on Florida’s list of construction class codes (class codes 5403 and 5645, Rule 69L-6.021). Florida therefore requires workers’ compensation as soon as you have one employee. Owners who are corporate officers or LLC members count as employees unless they hold an exemption (Florida Division of Workers’ Compensation).
If your work requires a state contractor license, that license also requires public liability and property damage insurance (Rule 61G4-15.003, Florida Administrative Code). Your county may also require proof of insurance before you start a job. So may any general contractor you work for.
My dad has a business where some fiberglass work and carpentry work is done we have 2 guys that come and work with us and they get a 1099. Do we have to have workers comp? We do have liability insurance Thanks, being harrassed from the owner of the whole property who allows others on their property with just liabilty.
I’m not sure I fully understand your question, but I will try to answer it. I am assuming that by “property owner” you mean the owner of a location where you are doing some work for a client. I am also assuming that by “have to have workers comp” you mean the statutory requirement to purchase the coverage.
The statutory requirements only say when a business must buy workers compensation. They do NOT say when a business becomes liable for its employees (or subcontractors). A business is ALWAYS liable for its employees (or subcontractors), regardless of the requirement to buy the coverage.
For example, a retail store has one owner and two sales reps. The law does not require it to carry workers compensation, because a non-construction business must carry the coverage with four or more owners and employees. The owner would still be liable if a stock shelf fell and hurt one of the sales reps. This is why some property owners require anyone doing work on their property to carry the coverage, even if the law does not require it.
In any construction business, the statutory requirement to purchase coverage starts with the first employee. Carpentry counts as construction. Many small businesses believe they can get around this requirement by paying the people who work with them as 1099 contractors. Unfortunately, that is not the measure the Florida Department of Labor uses to define an independent contractor.
So these individuals are sometimes still considered statutory employees. This means they are employees as far as the state is concerned, but they are paid as independent contractors. The workers compensation statutes treat statutory employees as regular employees. This is another reason some property owners require businesses to have the coverage. They don’t want to be responsible for statutory employees.
In conclusion, the property owner may ask you to carry the coverage even though you may not be legally required to purchase it. An accident could still become the property owner’s responsibility if there is no coverage in place.
What other insurance should a Carpentry Contractor consider?
Business Personal Property, Contractors’ Equipment and Tool Floater, Employee Dishonesty, General Liability, Employee Benefits Liability, Umbrella Liability, Automobile Liability and Physical Damage, Hired and Non-ownership Auto, Workers Compensation
Can you provide insurance anywhere in the state?
We have helped customers all across the state of Florida. Below are some of the cities we have done business in.
- Jacksonville
- Miami
- Tampa
- St. Petersburg
- Orlando
- Hialeah
- Tallahassee
- Fort Lauderdale
- Port St. Lucie
- Pembroke Pines
- Cape Coral
- Hollywood
- Gainesville
- Miramar
- Coral Springs
- Clearwater
- Miami Gardens
- Palm Bay
- West Palm Beach
- Pompano Beach